
Introduction
Receiving a settlement can feel like a long-awaited relief after a legal battle. However, the process of managing and distributing settlement funds—while also considering tax implications—can be complex, especially with multiple claimants or intricate financial circumstances. This is where a Qualified Settlement Fund (QSF) can be invaluable.
A QSF offers an organized, tax-advantageous solution for managing settlement funds. In this article, we’ll explore what QSF means, its purpose, and how it works. By the end, you’ll understand why a QSF might be the best option for lien and judgment settlements, tax planning, and efficient fund distribution.
Before diving in, use our settlement tax calculator to estimate your potential tax liability and see how planning tools like a QSF fit into your overall picture.
What is a Qualified Settlement Fund (QSF)?
A Qualified Settlement Fund (QSF) is a special account established to manage settlement proceeds in legal cases. Created under Section 468B of the Internal Revenue Code and corresponding Treasury regulations, it allows for the efficient management and distribution of settlement funds. A QSF provides plaintiffs with time to make financial decisions while granting defendants immediate and full release from their obligations.
This structure is particularly useful when there are multiple claimants or when complex tax and distribution considerations arise. It ensures all parties’ interests are managed fairly and compliantly.
Purpose of a Qualified Settlement Fund
The primary purpose of a Qualified Settlement Fund is to hold and manage settlement funds until they are distributed. Here’s how it works:
- Immediate Release for Defendants: Defendants transfer the settlement amount into the QSF, allowing them to fulfill their obligations and step out of the process.
- Flexibility for Plaintiffs: Plaintiffs gain time to plan their financial strategies, such as tax planning, lien resolution, or exploring structured settlements.
Common Scenarios for QSF Use:
- Multiple Plaintiffs: A QSF simplifies the distribution process in cases with numerous claimants.
- Time to Plan: Because the plaintiff has not yet received the funds, a QSF preserves time to evaluate liens, trusts, structured settlements, and tax questions before deciding.
- Structured Settlements: QSFs enable plaintiffs to fund structured settlements, spreading payments over time.
Single Claimant vs. Multi-Claimant QSFs
While Qualified Settlement Funds are often used in multi-claimant cases, they also benefit single-claimant situations:
- Single-Claimant QSFs: Can provide time to plan for a significant settlement. Whether a single claimant satisfies the requirements of the § 468B regulations is not settled (we believe it likely does), the IRS has not ruled on it, and not all annuity carriers will fund from a single-claimant QSF.
- Multi-Claimant QSFs: Streamline complex settlements by organizing funds for distribution among multiple plaintiffs.
It’s important to note that structured settlement annuities can generally be funded through multi-claimant QSFs. For single-claimant QSFs, only select annuity providers accommodate this. Contact us to discuss these nuances and how they may impact your case.
How Qualified Settlement Funds Work
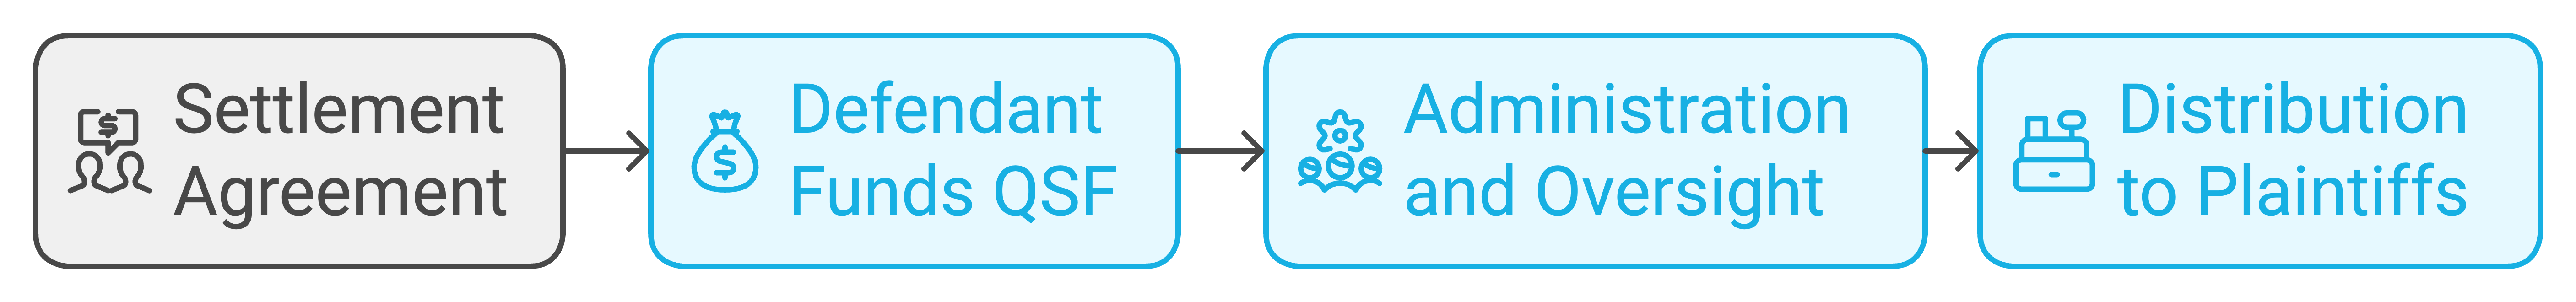
A QSF is established by court order and is managed by a neutral third-party administrator or trustee. Here’s an overview of the process:
- Defendant Funds the QSF: The settlement funds are transferred into the QSF, fulfilling the defendant’s obligations.
- Administration and Oversight: The QSF administrator is responsible for managing the fund and meeting its tax and reporting obligations.
- Distribution to Plaintiffs: Plaintiffs can choose from several options, including lump-sum payments, structured settlements, or customized payouts.
By transferring control of settlement funds to a QSF administrator, this process places responsibility for managing the funds and meeting tax requirements with the administrator.
How Do Distributions From a Qualified Settlement Fund Work?
Distributions from a Qualified Settlement Fund are tailored to plaintiffs’ financial needs and preferences. Options include:
- Lump-Sum Payments: Immediate access to the full settlement amount.
- Structured Settlements: Payments spread over time, offering ongoing income and potential tax benefits.
- Customized Payouts: A mix of lump-sum and periodic payments to suit individual financial goals.
Administrators work closely with plaintiffs and their settlement planners to ensure distributions align with each person’s unique situation.
Benefits of Using QSFs
Using a Qualified Settlement Fund offers several key advantages:
- Time to Decide: A QSF avoids constructive receipt while the plaintiff decides. Tax treatment depends on the nature of the claim — a physical injury recovery is generally excludable under IRC § 104(a)(2) whether or not a QSF is used.
- Control Over Timing: Plaintiffs decide when and how they receive their settlement funds.
- Simplified Structured Settlements: QSFs streamline the setup process for structured settlements, even when defendants cannot directly fund annuities.
- Efficiency in Multi-Claimant Cases: QSFs organize and simplify the distribution process, reducing disputes and delays.

Qualified Settlement Fund Tax Treatment
For tax purposes, a Qualified Settlement Fund is treated as a separate legal entity. Here are some important points:
- The QSF pays taxes on any interest or investment income it generates.
- Plaintiffs generally do not report their share as income until they receive distributions. Whether a distribution is taxable at all depends on the nature of the underlying claim.
This flexibility is what allows plaintiffs to explore options such as structured settlements or special needs trusts, helping them manage their tax burden effectively.
Common Challenges of Qualified Settlement Funds
While QSFs offer many benefits, they can also present challenges:
- Administrative Costs: Setting up and managing a QSF involves fees. However, our team partners with low-cost administrators to minimize these expenses.
- Complexity: Establishing a QSF requires legal paperwork and compliance with IRS regulations. Most QSFs can be set up quickly with our assistance.
- Reporting Requirements: QSFs must meet strict IRS reporting rules. We work with experienced administrators who handle these obligations.
Frequently Asked Questions (FAQs)
What Are the Costs Associated with Setting Up a QSF?
The cost of a QSF is typically $2,500, including administrative and tax return fees. In some cases, our team covers these costs to make using a QSF even more accessible.
How Long Can Funds Remain in a Qualified Settlement Fund?
Funds can remain in a QSF until all distributions are complete. This gives plaintiffs ample time to make financial decisions.
What Happens if a QSF Is Not Managed Properly?
Improper management can lead to compliance issues and tax penalties. Working with experienced administrators, like those we recommend, minimizes these risks.
Conclusion
A Qualified Settlement Fund is a powerful tool for managing complex settlements, offering benefits such as time to plan, structured settlement opportunities, and streamlined fund distribution. By understanding the QSF meaning and its applications, you can maximize the value of your settlement.
Navigating the complexities of a Qualified Settlement Fund requires expertise. At Amicus Settlement Planners, we specialize in guiding clients through the setup, administration, and distribution processes of QSFs.
Considering a QSF for Your Settlement?
Schedule a call with Amicus Settlement Planners today. Our team will help you navigate the ins and outs of QSFs, and work with administrators who handle the filing and reporting requirements. Let us simplify the process so you can focus on making the most of your settlement.
Important information about this article
This article is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Amicus Settlement Planners is not a law firm and is not a registered investment adviser.
Whether a qualified settlement fund is appropriate, and how it will be treated for tax purposes, depends on the facts of a particular case. Some applications are more settled than others. In particular, the use of a QSF for a single claimant involves unsettled questions of federal tax law, and not all annuity carriers will accept funding from a single-claimant QSF.
Amicus Settlement Planners is compensated in connection with settlement planning services and has business relationships with fund administrators and annuity carriers.
Before establishing a QSF, consult your own tax advisor and legal counsel, who can evaluate your specific circumstances.


