
Attorney Fee Deferralplan the tax on a large fee
If you practice on contingency, your income arrives in large, unpredictable chunks. One good year can push most of a fee into the top bracket, and the year after can be thin.
We model it, then give you a straight answer, including when the answer is to just take the fee.

This page is an overview. It covers what the strategy is, what it requires, and what you should weigh before doing it. There is a good deal more to say about the underlying tax law, and we are happy to go through it in as much depth as you want on a call.
What an Attorney Fee Deferral is
A fee deferral is an agreement, made before you have earned or become entitled to receive a contingent fee, that some or all of that fee will be paid to you over future years instead of at settlement.
The vehicle we lead with is a structured attorney fee: a fixed schedule of future payments funded by an annuity issued by a life insurance company. The obligation to pay you is assigned to an assignment company, which purchases the annuity and remains the party that owes you the money. Funding goes directly from the defendant or its insurer to the assignment company. It never passes through you or through your firm's trust account.
Two features of that structure matter, because they are both the reason it works and the source of its limitations:
The assignment company does. What you hold is a contractual right to receive future payments.
You are a general unsecured creditor of the assignment company. Nothing is set aside in your name, beyond the reach of that company's other creditors.
This is not a retirement account. There is no contribution, no deduction, no balance belonging to you, and no early withdrawal. Anyone describing it in those terms is describing something else.
The Law Behind It
The controlling authority is Childs v. Commissioner, 103 T.C. 634 (1994), affirmed by the Eleventh Circuit in 1996.
In Childs, attorneys agreed before settlement to take their fees as future periodic payments funded by annuities. The Tax Court held they were not taxed until the payments were actually received, because they did not own the annuities, held nothing more than a general creditor's claim, and could not get at the money at will.
Childs remains the only court decision addressing the deferral of contingent attorney fees. It was decided in the taxpayers' favor and has not been overruled.
That is the short version. The reasoning matters quite a bit in practice, and we can walk through it with you and with your tax advisor in detail.
The rules turn on timing. So does your window.
The agreement has to be in place before your settlement is finalized. If a case is close, it is worth a conversation now, not after.
Free, no obligation. Or call (801) 683-7362.
What Has to Be True
The features that carried the day in Childs are not abstractions. They translate into specific requirements:
What You Give Up
Deferral is a genuine trade. The features that support the tax treatment are the same ones that constrain you:
The schedule is fixed. If your circumstances change, you cannot accelerate it, borrow against it, or unwind it.
You are an unsecured creditor. Payments depend on the continued claims-paying ability of the assignment company and the issuing life insurance carrier. Guarantees are backed by the issuer, not by any government agency and not by us.
An annuity-funded structure produces a contractually determined stream. It is not designed to track market returns, and in a strong market it may well trail what you would have earned by taking the fee, paying the tax, and investing the rest.
Payments many years out buy less than the same nominal dollars buy today.
Tax rates in your distribution years may be higher than today's, and the law governing these arrangements could change.
See below.
Where the IRS Stands
The IRS has taken positions contrary to the treatment described above with respect to certain fee deferral arrangements, and it announced an examination campaign concerning deferred legal fees in December 2024. That campaign is still active. The arrangements drawing attention are generally ones in which fees are moved to a third party but the attorney can still reach the money before the schedule says so. A structured fee of the kind described on this page has no such feature, which is one reason we lead with it.
None of which is a prediction about how the IRS would treat your particular arrangement. This area is unsettled, capable tax professionals disagree about it, and you should get your own advice. We are glad to go through the current guidance in detail on a call.
See it modeled on your case
We will run a structured fee against simply taking it, from multiple carriers, and tell you which one wins on your facts.
Book a callFree, 30 minutes, no obligation.
Or call (801) 683-7362.
Fixed schedule, funding you do not own, no accessHigher tax risk
More flexibility or upside, more exposure
The further an arrangement moves from the facts the Tax Court approved, the more tax risk it carries. We will tell you where any option sits.
Other Deferral Vehicles
Other fee deferral vehicles exist, and we are happy to walk through them with you.
Our general view is simple: the further an arrangement moves from the facts the Tax Court approved in Childs, the more tax risk it carries. The features that did the work in that case, a fixed schedule set before the fee is earned, funding you do not own, and no ability to accelerate, borrow against, or pledge the payments, are the ones worth keeping. Arrangements that relax them may offer more flexibility or more investment upside, and they take on more exposure in exchange.
If you want to consider something other than an annuity-funded structure, we will lay out the pros and cons of each option and tell you where we think the risk sits. Then take that analysis to your own CPA and tax counsel.
Who This Tends to Fit
It tends to fit
- Contingency fee attorneys facing an unusually large fee in a single year.
- Attorneys whose income swings widely and who want to smooth it out.
- Attorneys who expect to be in a lower bracket in the years they take distributions.
- Attorneys building long-horizon income who can genuinely afford to give up access to the money.
The other side
It tends not to fit attorneys who may need liquidity, who are uncomfortable holding an unsecured claim, or who want investment upside on the deferred amount.
Have a case that may settle?
We will model a structured fee against simply taking it, so you can see the tradeoff in numbers before you decide anything.
Or call (801) 683-7362. No obligation.
How We Work
Conversation
We learn about the case, the timing, and what you are trying to accomplish.
Illustration
We model payment schedules from multiple carriers so you can compare them against simply taking the fee.
Your advisors review
We expect you to take the proposal to your own CPA and tax counsel. We will talk to them directly if that helps.
Documentation and funding
If you go forward, the agreement is put in place before settlement is finalized, and the defendant or carrier funds the assignment company directly.
Payments
You receive payments on the agreed schedule.
Explain the options, model the numbers, and place the annuity.
We do not give you legal or tax advice, we do not opine on whether a deferral will be respected on your facts, we do not administer any deferral program, we do not hold your funds, and we are not the party that owes you the payments.
What Makes Us Different From a Structured Settlement Broker
Most of the people who will offer to structure your fee are insurance producers. Placing the annuity is the entire job, and the only question they are equipped to answer is which carrier pays the most. That is not the same work.
Sells the annuity
- An insurance producer whose entire job is placing the annuity.
- The only question they can answer is which carrier pays the most.
- One license, so they see one of the four questions a deferral raises.
- A single product, so a fee structure is always the answer.
Reads the law first
- Licensed attorneys who have read the case law, IRS guidance, and provider tax opinions.
- A team of attorneys, a CPA, and CFP® professionals across all four questions.
- Fee deferral is one tool among many across full settlement planning.
- We regularly tell attorneys to take the fee and pay the tax when that is the right call.
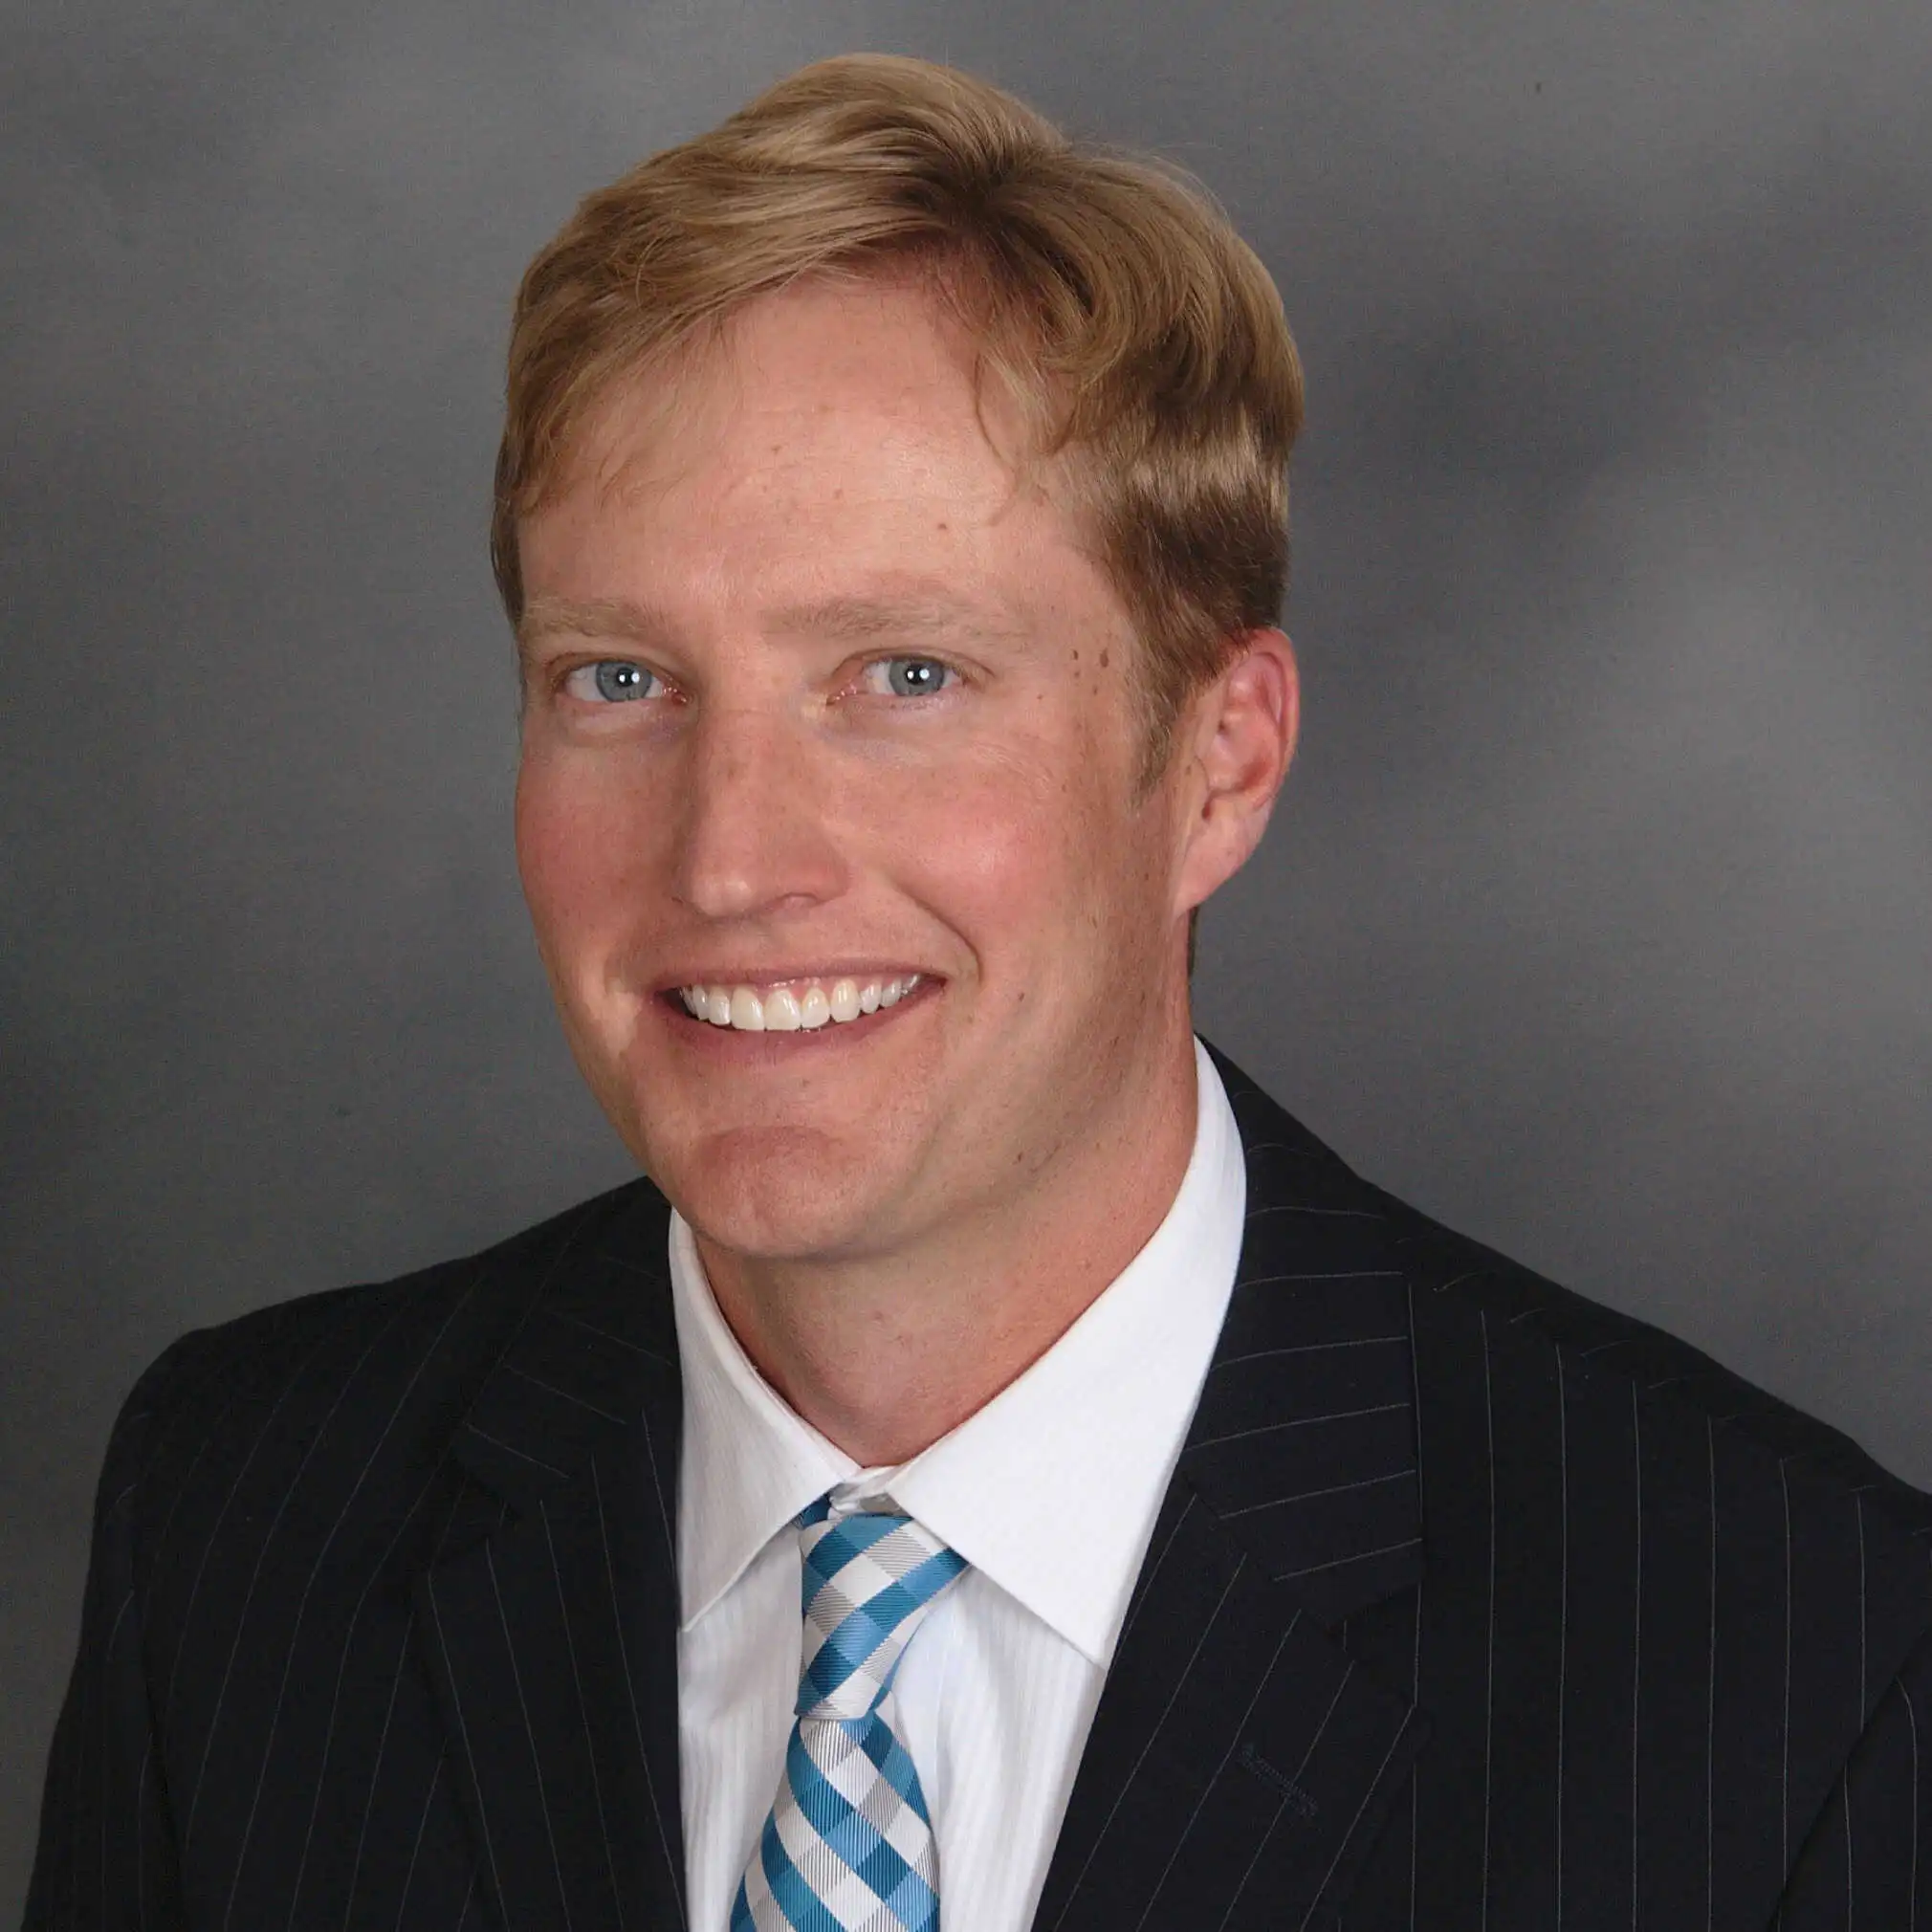

We are lawyers
Gregory Maxwell and Daniel Maxwell are both licensed attorneys. We have read the case law, the IRS guidance, and the provider tax opinions ourselves. When we tell you what the mechanics have to look like and why timing matters, that comes from the primary sources rather than from a carrier's one-page sell sheet. We are not acting as your lawyer and nothing we say is legal advice, but the analysis behind our recommendation is one we did ourselves.
A full advisory team
Our team includes licensed attorneys, a CPA, and CERTIFIED FINANCIAL PLANNER™ professionals. A fee deferral is at once a tax question, a cash flow question, an investment question, and an estate question. Firms holding only one of those licenses tend to see only one of those questions.
Fee deferral is one tool among many
We do settlement planning across the board: structured settlements for plaintiffs, qualified settlement funds, government benefits preservation, trusts, and asset management. A firm whose only product is a fee structure will find that a fee structure is always the answer. We regularly tell attorneys to take the fee and pay the tax, because on their facts that is the right call.
We work with your advisors, not around them
We expect you to take our proposal to your own CPA and tax counsel, and we will get on the phone with them directly. An advisor who discourages that is telling you something.
We have done this a lot
We have worked with hundreds of contingency fee attorneys, on settlement planning for their clients, on their own tax planning, and on fee deferrals, and we model schedules from multiple carriers rather than steering you toward one. None of which is a guarantee of any result, for you or for anyone else.
Want a straight read on your case?
We will model a structured fee against simply taking it, from multiple carriers, and tell you which one wins on your facts.
30 minutes, no obligation.
How We Are Paid
You should know this before you talk to us. When we place a structured settlement annuity, we are paid a commission by the issuing life insurance company. That commission is not a separate charge to you and it does not reduce your payment stream, but we do have an economic interest in the transaction, and you should weigh what we tell you accordingly.
That is exactly why we send you to your own CPA and your own tax counsel. Their judgment is worth more than ours precisely because they are not paid in connection with the deal.
Frequently Asked Questions (FAQs)
Can a contingency fee attorney defer legal fees to a future tax year?
When does the agreement have to be in place?
Do I own the annuity?
Can I access the money early, or borrow against it?
Is this a retirement plan?
What happens if the insurance company fails?
What is the IRS position?
What does it cost me?
Talk It Through
If you have a case that may settle and you want to understand whether a structured fee makes sense, we will model it and give you a straight answer, including when the answer is that you should just take the fee. If you want to go deeper on the tax law than this page does, that is what the call is for.
Important Disclosures
Amicus Settlement Planners, LLC is a settlement planning firm based in Lehi, Utah, serving attorneys and plaintiffs nationwide. It is not a law firm, it is not a registered investment adviser, and it is not a broker-dealer. Nothing on this page is legal advice, tax advice, or investment advice, and nothing here creates an attorney-client relationship.
Certain Amicus Settlement Planners personnel are investment adviser representatives of Amicus Financial Advisors, LLC, a separate SEC-registered investment adviser that is not owned by Amicus Settlement Planners or by its principals. Investment advisory services are offered only through Amicus Financial Advisors, LLC. The attorneys named on this page are licensed to practice law but do not act as your attorney and provide no legal advice through Amicus Settlement Planners.
Attorney fee deferral involves unsettled questions of federal tax law. The IRS has taken positions contrary to the treatment described on this page with respect to certain arrangements, and has an active examination campaign concerning deferred legal fees. No outcome is guaranteed, and past results do not indicate future results.
Any attorney considering a fee deferral should obtain advice from their own CPA and their own independent tax counsel, who can evaluate the attorney's specific circumstances and who are not compensated in connection with the transaction.
Annuity guarantees are subject to the claims-paying ability of the issuing insurance company. Amicus Settlement Planners is compensated in connection with the placement of structured settlement annuities.
Last reviewed: 08/26/2026